You accept an offer, then reality hits your wallet
The offer looks clean on paper, and the number is usually high enough to quiet the nagging questions. Then the calendar starts filling up: a start date, an onboarding week, a benefits portal with deadlines, and a resignation window that can’t slip. Somewhere in that blur, the first real constraint shows up—cash timing. A larger salary doesn’t help much if a gap week lands between payroll cycles, or if the first check comes later than expected because of cutoffs.
Even before anything goes wrong, small “admin” choices start changing the outcome: how much to defer on day one, which health plan takes effect when, whether an annual bonus resets, whether unused PTO is paid out. It’s not panic, just the moment the wallet replaces the spreadsheet as the judge.
First paycheck shock: why higher salary pays less
The first pay stub is where the confidence wobbles. The annual figure went up, but the deposit looks strangely ordinary—or even smaller—because the switch changes the math around it. Payroll cutoffs often mean the first check covers fewer days, and some employers start you on a “partial period” without calling it that. If you left mid‑cycle at the prior job, you can end up with two smaller checks in a row right when moving costs are peaking.
Then the deductions arrive all at once. A new benefits election can pull premiums immediately, sometimes with catch‑up to align with the company’s billing cycle. Withholding can also jump if the new payroll system defaults to a more conservative tax setup until forms are processed. And if you decide to “do the right thing” and max the 401(k) early, that larger deferral hits the first check harder than expected. The raise is real; the timing and defaults are what make it feel missing.
Health coverage gaps that quietly create big bills
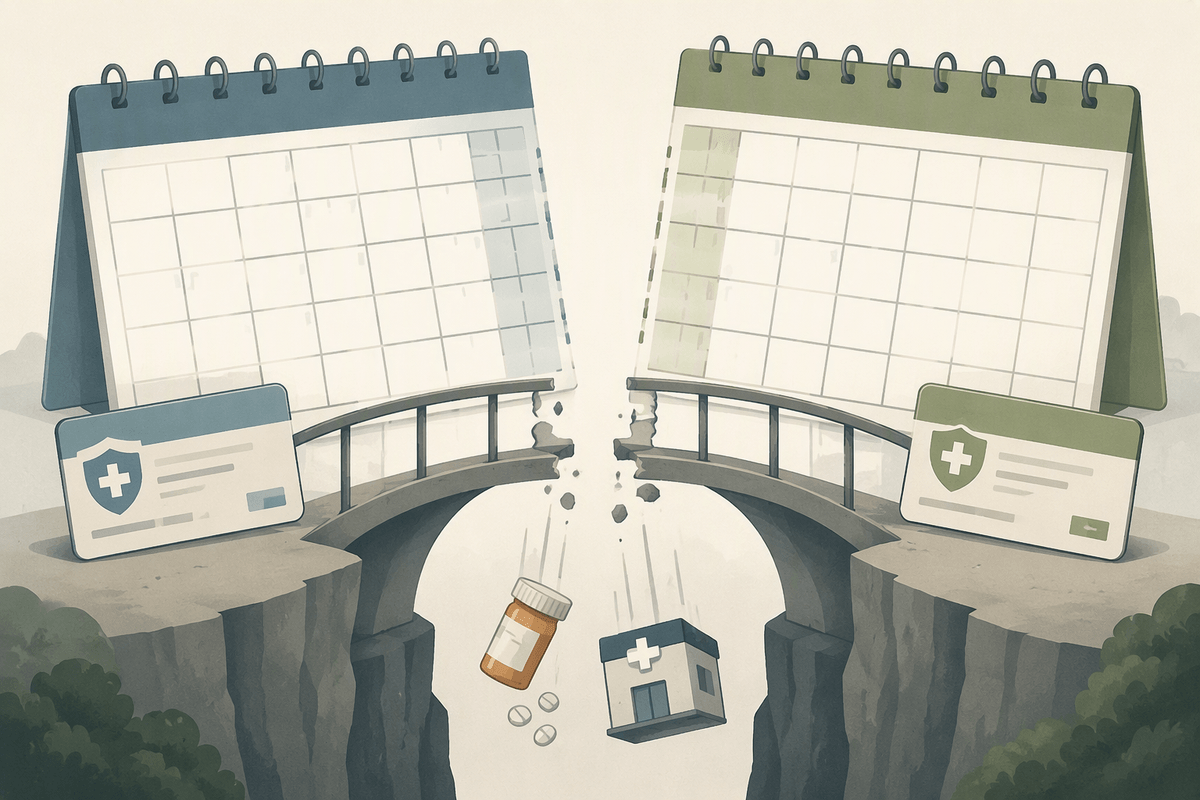
The benefits portal makes it feel handled, but the timeline is usually the fragile part. One employer ends coverage on your last day; another keeps it through the end of the month. The new plan might begin on day one, or it might not start until the first of the next month. A one‑week gap can turn into three weeks if your start date lands after a cutoff, and it rarely announces itself until you’re already between cards.
That’s when “normal” expenses get priced like a mistake. A routine prescription refill hits retail pricing. A child’s urgent care visit that would’ve been a copay becomes a full bill. Even if COBRA is available, the decision is time‑sensitive and expensive: you’re paying the full premium, and the election paperwork can lag while appointments keep happening. People assume the risk is a catastrophe; more often it’s a handful of ordinary services that land in the gap.
The quieter bill is the reset. New deductibles and out‑of‑pocket maximums don’t follow you, so switching mid‑year can mean paying “first‑dollar” costs again—right after you already met most of the prior plan’s deductible. If you’re comparing offers, the question isn’t just which plan is better; it’s whether the effective date and the deductible reset make the first few months materially more expensive than the spreadsheet suggests.
The 401(k) fork in the road you didn’t expect
Retirement contributions feel like the one thing you can keep steady, but the job switch forces a decision sooner than most people expect. The old 401(k) may stop taking contributions on a final payroll cutoff, while the new plan might not let you enroll until after a waiting period. If you were pacing your deferrals to hit a target by December, that gap can quietly break the plan and you only notice when the year is nearly over.
Then the fork shows up: roll the old balance, leave it, or move it to an IRA. Rolling sounds clean, but it can freeze the money for weeks and it’s easy to miss a form, a “made payable to” detail, or a required signature. Leaving it behind avoids timing risk, yet it can mean higher fees, fewer fund choices, or losing access to a loan you were counting on for near-term liquidity.
On the new side, match rules aren’t interchangeable. Some employers match per paycheck, not “true-up” at year-end, so front-loading deferrals to catch up after a gap can accidentally reduce the match. It’s not a morality play about saving; it’s a sequencing problem with deadlines, payroll systems, and a real dollar penalty if the timing is off.
Bonuses and equity: timing can erase real value
The next surprise is how quickly “total comp” turns into a calendar problem. If your annual bonus is based on being employed on a specific payout date, resigning a few weeks early can turn last year’s performance into zero dollars. Even when the plan sounds prorated, the fine print often ties eligibility to a minimum service period or an “active on payout” rule. The constraint isn’t effort; it’s that the decision date is usually earlier than the money date.
Equity behaves the same way, just with more moving parts. Unvested RSUs typically vanish at termination, and options can trigger a short post-termination exercise window that forces a cash decision when liquidity is already tight. On the new offer, the grant you’re excited about may not start vesting for months, and refresh grants can be discretionary. When you compare offers, map each payout and vest date to a real month-by-month cash plan, not a headline number.
One-time costs and cash crunch during the switch
By the time you’ve mapped bonus dates and benefit effective periods, the messier line items start showing up in your checking account. The switch creates one-time costs that don’t feel negotiable: replacing a laptop that was “fine” until the old employer wants it back immediately, paying for a pre-employment drug screen or credentialing fee that gets reimbursed later (or not), and covering higher commuting or parking costs before the first full paycheck arrives. Even a modest moving stipend can land after you’ve already floated the expense.
The cash crunch is usually about overlap and timing, not lifestyle. A final paycheck may be smaller because of partial periods or benefit deductions, while the first check at the new job can be delayed by a payroll cutoff. In the middle, COBRA premiums, deductible resets, and an option exercise window can all compete for the same dollars. The practical constraint is liquidity: having two months of “boring” cash on hand often matters more than whether the offer wins on paper.
A simple offer map to avoid financial surprises
After the last-minute payments and weird payroll dates, the cleanest fix is a one-page “offer map” built around months, not annual numbers. Put start date, first payroll date, and benefit effective date on the same line, then list every cash event that depends on those dates: sign-on, first bonus eligibility, RSU cliff, match start, and any waiting periods. The constraint is that one missed cutoff can move real money by 30 days.
Under that timeline, add four buckets with estimated dollars: (1) net pay in month one, (2) health coverage gap risk (COBRA or bridge plan), (3) retirement sequencing (deferral plan vs match rules), and (4) one-time outflows (move, equipment, commuting, reimbursements). If the map shows a negative month, negotiate timing—start date, sign-on paid in first check, or reimbursements up front—before the resignation email goes out.