You notice three “protection” charges on one bill
The bill is already higher than expected, and then the line items start to repeat: “Device Protection,” “Payment Protection,” “Identity Protection.” None of them looks large on its own, but together they add up to a real monthly number—and the names are vague enough that it’s hard to tell whether they’re insurance, a service plan, or a fee you accidentally agreed to. The tension is practical: cancel the wrong thing and you could lose a benefit you’ve relied on without realizing it.
Before touching anything, mark each charge with three notes: what it claims to cover (the noun matters more than the marketing word “protection”), where else you might already have it (auto/home/renters, health, credit cards, employer benefits), and whether it’s tied to a contract or financing. That quick pass usually exposes the first overlap without forcing a decision yet.
Pick one policy to audit before you touch anything
The next move isn’t canceling; it’s choosing one item to interrogate first so you don’t lose track of what overlaps with what. Start with the charge that’s easiest to verify in writing within 15 minutes—usually the one attached to a loan, a device installment plan, or a credit card add-on—because there will be a disclosures page, a certificate, or a benefits guide you can pull up without calling anyone. “Identity” and “payment” products tend to be the fastest to document; “device protection” often hides deductibles and replacement limits that matter.
Open the document and extract four fields into a note: the covered event (exact triggers), exclusions that would block the most likely claim, the benefit cap (per incident and per year), and the cancellation/retroactive refund rule. If you can’t find those four quickly, that’s a signal in itself: you’re paying for something you can’t audit under time pressure, and you should pause before it quietly renews again.
The common double-pay traps hiding in plain sight
Once one add-on is documented, the overlaps get easier to spot because they show up as the same “covered event” repeated across different products. The most common trap is paying for accidental damage or theft twice: a phone “device protection” plan plus a credit card benefit (or homeowners/renters personal property coverage) that already responds, with different deductibles and claim rules. Another frequent double-pay is “payment protection” on a financed purchase while you also carry separate disability or unemployment coverage through work—both trigger on income disruption, but one may have a short benefit window and strict eligibility language.
Identity products are the quietest repeat charge. Many renters/homeowners policies include identity fraud expense coverage, some employers include monitoring, and many cards offer limited fraud support—so the add-on you’re buying may be mostly concierge and credit monitoring, not actual reimbursement. Then there are roadside and rental car overlaps: auto insurance, an auto club membership, and a card benefit can all promise towing or collision damage waivers, but the limits (miles, vehicle type, “secondary vs primary”) decide whether you’re paying twice for the weaker one.
A quick checklist helps: same trigger, same property/person, and the smaller cap or worse exclusions is the one you question first—especially if canceling takes effect immediately with no prorated refund.
What went wrong last time you filed a claim
Pull up the last claim you actually filed—even if it was small—and read it like a post‑mortem. The fastest way to avoid cutting the wrong “protection” is to see where the process broke when money was on the line. Start with the denial letter, adjuster notes, or the email thread and isolate the single sentence that explains the outcome: excluded cause, late reporting, missing documentation, or the loss falling under a different policy than you assumed. If you can’t find that sentence, that’s friction worth pricing in, because a benefit you can’t operationalize under stress behaves like no coverage at all.
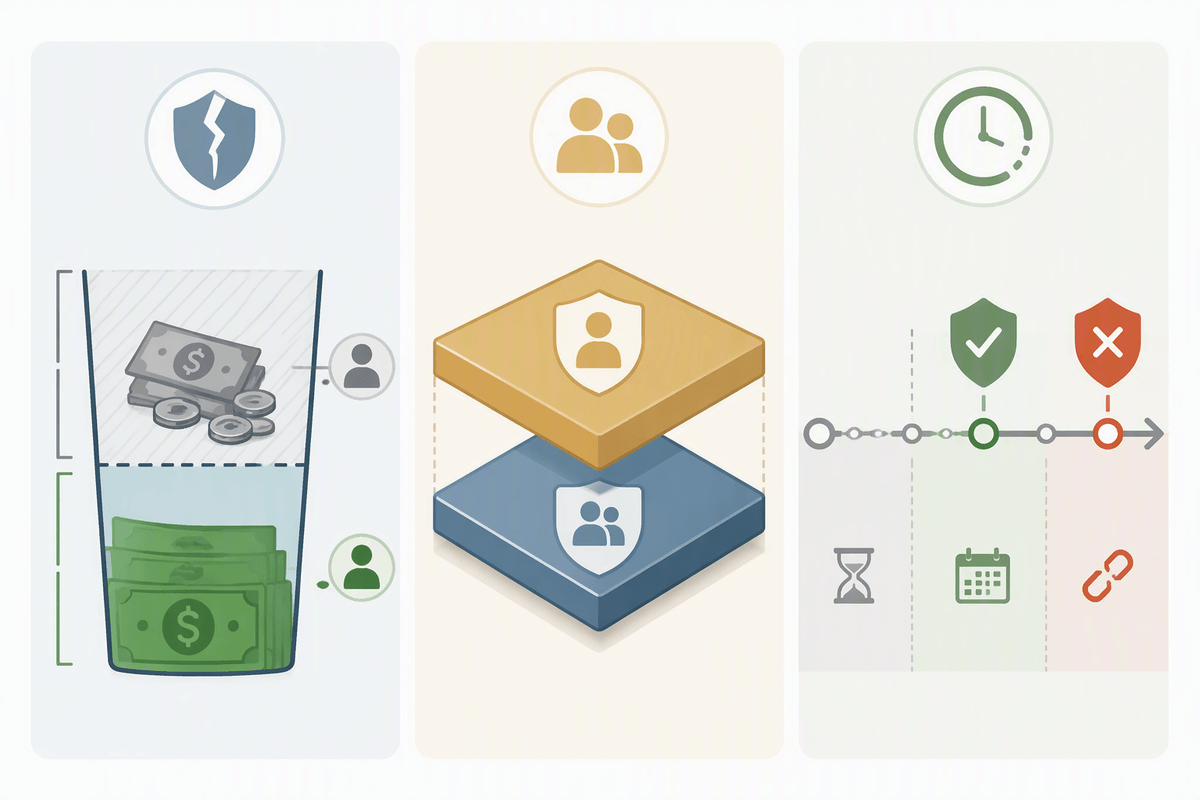
Then compare what you expected to happen versus what the contract required. Three patterns show up: (1) deductible shock (device plans and auto comp often “work” but still leave a painful out‑of‑pocket), (2) coordination rules (credit card coverage being secondary, or requiring the entire purchase on the card), and (3) eligibility timing (waiting periods, prior damage, lapse/arrears on an add‑on). When an add‑on failed for a rule you’d likely hit again, it’s a stronger cancellation candidate than the one that paid cleanly—even if the monthly price is similar.
Your risk line: what you can self-insure safely
After that claim post‑mortem, the question shifts from “what overlaps?” to “what loss could I absorb without scrambling?” The cleanest way to draw your risk line is to look at cash, not fear: take your liquid emergency fund and subtract the next 30 days of unavoidable bills. What’s left is the maximum surprise cost you can pay quickly without missing rent/mortgage, utilities, or minimum debt payments. If that number is $800, then a $1,500 deductible doesn’t just “hurt”—it breaks the plan.
Now pressure‑test the add‑ons against that line. If the worst‑case out‑of‑pocket after any deductible stays below your number, self‑insuring is usually rational: minor phone damage, a short tow, a single appliance repair, a small identity‑theft expense. The trap is low monthly premiums masking high friction: narrow triggers, short benefit windows, and reimbursement paperwork. If a product only pays after you front the cost, treat it like you’re self‑insuring anyway—just with a filing requirement.
Five questions to ask before you cancel anything
The urge is to start clicking “cancel” as soon as an overlap shows up, but timing and paperwork are where people get burned. If the add-on is tied to financing, canceling mid-cycle can trigger a billing mess; if it’s bundled, removing one piece can reprice the rest. So before anything changes, it helps to pin down five answers in writing—screenshots count—so you can unwind it later if the carrier “can’t find” the request.
First: what exact loss does this pay for, and what’s the maximum it will actually reimburse after deductibles and caps? Second: what other policy already responds to that same trigger, and is this one primary or secondary? Third: what exclusions map to your real life (rideshare use, pre-existing damage, water types, unattended theft, unemployment definitions)? Fourth: what happens on the cancellation date—immediate termination, end of billing cycle, or prorated/retro refund—and is there a waiting period to re-enroll? Fifth: if you cancel and a claim happens next month, what’s the dollar amount you’d eat without destabilizing the budget?
Cancel carefully: sequence, proof, and follow-up reminders
Once the candidate is clear, the safest move is to control the sequence. Don’t cancel the overlapping add-on until the “primary” coverage is confirmed active (policy number, effective dates, and the exact benefit line) and you’ve saved that proof. Then cancel in a way you can document: confirmation email, chat transcript, or a screenshot that shows the date/time, product name, and refund terms. If the rep says “it will drop next cycle,” ask for the precise end date.
Set two reminders: one for the next statement to verify the charge is gone, and one 30 days later to confirm nothing else was repriced. Keep a single folder with all confirmations; billing disputes are easiest when you can attach receipts, not recollections.