Your account is down—what now, exactly?
The number on the screen is smaller, and it’s not just “a red day” anymore. Maybe the drop is big enough that it changes what you thought you had for retirement, or it’s happening right as a tax bill, tuition payment, or home project is coming due. The pressure is rarely abstract: headlines get loud, friends start swapping predictions, and the urge is to do something that feels clean and final.
Before choosing a move, the useful question is what kind of problem you’re solving. Is this a short-term cash problem (money needed in months), a risk problem (too much stock for your tolerance), or a plan problem (a portfolio that no longer matches your target mix)? Those answers decide whether the next action is trimming, pausing, rebalancing, or simply waiting with intent.
When a drop stops feeling temporary
After a few down weeks, the story shifts from “mean reversion” to “regime change.” It’s usually not the single -2% day—it’s the grind: rallies that fail, new lows that keep showing up, and a portfolio that’s still sinking after you stopped checking it hourly. The constraint is time. If this drawdown is overlapping with a known spend (next year’s taxes, a remodel deposit, a tuition schedule), the market doesn’t have to be “broken” to create real damage.
What matters is whether your plan can absorb a longer recovery window without forcing sales. If your equity sleeve is down 20–30% and the calendar is tight, sequence-of-returns risk becomes personal. In taxable accounts, losses can be useful, but only if you’re not panic-selling winners to “balance it out.” The next decision point is simpler than it feels: which dollars must be protected from needing the market’s permission to be available?
The first fork: protect cash needs
That’s the fork, and it’s not philosophical. Any dollars that have a job in the next 6–24 months—property taxes, tuition, a down payment, even a planned Roth conversion tax bill—can’t be treated like “long-term money” just because they sit inside a brokerage account. If the market forces you to sell into weakness to meet a date on the calendar, the loss stops being temporary and becomes structural.
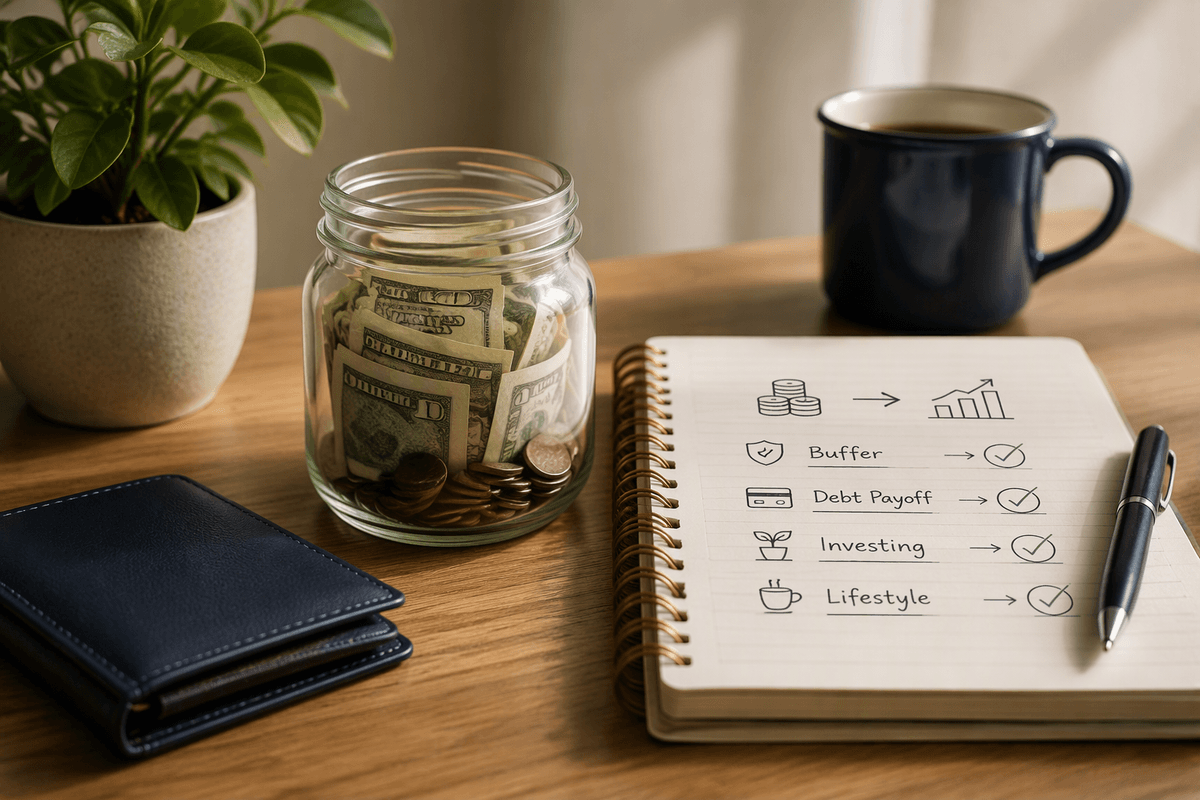
So the first move is a cash-needs inventory, not a market call. List the next two years of known outflows and map them to assets that don’t require a rebound: cash, Treasury bills, money market funds, or short-duration bonds you’re willing to hold to maturity. If you’re short, the uncomfortable answer may be raising cash now—even at a bad price—because the alternative is worse: being a forced seller later, when spreads are wider, headlines are uglier, and taxes are harder to control.
Selling to stop the pain, and its cost
Raising cash can feel like relief because it turns a moving target into a fixed number. The cost shows up fast, though: whatever you sell stops participating in any rebound, and the market has a habit of recovering in sharp bursts that are easy to miss if you wait for “clarity.” If the sale is happening inside a taxable account, the trade can also create a tax bill at the worst moment—selling appreciated lots to “get safe” can trigger capital gains, while selling at a loss helps only if it fits a broader tax plan rather than a reflex.
The other cost is behavioral and mechanical. In stressed markets, bid-ask spreads widen, and you may accept worse pricing just to be done. Then comes the awkward question of re-entry: buying back higher feels like admitting a mistake, so the portfolio stays underinvested longer than intended. If selling is the move, it works best when it’s sized to a specific cash need or target allocation, not to a feeling.
Holding steady isn’t passive if it’s intentional
There’s a moment after the “sell something” impulse passes when doing nothing starts to look like denial. But holding can be an active choice if it’s tied to a specific decision: your cash needs are already covered, your target allocation still makes sense, and you’re willing to accept a longer recovery window without forcing trades.
The constraint is psychological and procedural. If you’re holding, it has to be paired with guardrails that reduce the chance of a sloppy pivot later: a written rebalancing band (for example, equities drift 5% off target before you act), a schedule for checking balances (monthly, not hourly), and a rule about what would actually change your plan (job loss, a new spending date, a confirmed mismatch in risk level). That turns “waiting” into a monitored position rather than a frozen reaction.
Rebalancing: the uncomfortable move that restores logic
When the portfolio has drifted far enough, the next move isn’t about confidence—it’s about math. A 60/40 that quietly became 70/30 after a strong run can flip the other way during a selloff, leaving you with less equity risk than you planned just when expected returns are higher. Rebalancing asks you to do the opposite of the mood: add to what just hurt and trim what held up.
The constraint is friction: taxes, transaction costs, and the fear of “catching a falling knife.” In taxable accounts, it often works better to direct new contributions and dividends toward the underweight sleeve before selling anything. If you do sell, lot selection matters—raising cash by trimming bonds in a downturn can undo the stability they were meant to provide, while selling winners can create gains you didn’t budget for.
Done well, rebalancing isn’t a prediction. It’s a pre-committed rule that restores the portfolio you meant to own, at a time when instinct would rather wait for permission from headlines.
Adding cash: safer choice, hidden trade-offs
After rebalancing starts to feel like “moving pieces around,” adding cash looks like the cleaner fix: transfer money in, buy what’s underweight, and skip the drama of selling. It can be genuinely stabilizing, especially if it reduces the chance you’ll have to liquidate anything for near-term needs. The constraint, of course, is that spare cash is rarely spare—maybe it’s earmarked for a house project, an emergency fund target, or simply higher day-to-day costs.
The trade-off is quieter. New cash can accidentally raise your effective risk if you deploy it too fast, then the market leg down hits harder because you have more dollars exposed. In taxable accounts, it can also complicate tax-loss harvesting windows (wash-sale rules) if you buy “too similar” right after selling a loser. If adding cash is the move, it works best with pacing—scheduled buys—and a clear limit on how much liquidity you’re willing to convert into market time.
A calmer playbook for the next ugly week
Next week will probably feel like it’s daring you to react. The constraint is timing: if you’re trading on a lunch-break headline or a late-night futures move, you’re effectively letting the market set your calendar. A calmer approach is smaller and stricter—two check-ins (say Tuesday and Friday), and no “exceptions” unless an actual cash need changed.
At each check-in, run the same three prompts. First: are the next 6–24 months of expenses still matched to cash or near-cash, or did the drawdown create a funding gap? Second: did allocation drift past your rebalance bands, and can you correct it with contributions/dividends before selling in taxable? Third: if you must trade, which lots minimize avoidable taxes and wash-sale mistakes? Then stop. The goal is consistency, not catharsis.