Two offers, one paycheck, one safety net
The two emails land within an hour: one is a clean salary bump, the other is a lower number wrapped in “total rewards.” Both feel like a win until the calendar shows open enrollment in six weeks, your partner’s contract ends in March, and the mortgage rate resets next summer. The nervous part isn’t greed—it’s the gap between what’s promised on paper and what actually protects you when a year gets messy. Before anyone counteroffers, it helps to notice what’s really scarce: one paycheck to run the month, and one safety net to absorb surprises.
When you compare offers, the paycheck is only the part that shows up every two weeks. The safety net is everything that keeps a bad quarter from becoming a financial event: employer health premiums, deductible exposure, disability coverage, severance likelihood, and retirement contributions that keep compounding even if raises slow down. A higher salary can still leave you more fragile if it comes with a high-deductible plan, a weaker match, or a probation period that delays benefits. Start by writing down what must be true for you to feel “covered” this year—then see which offer actually meets it.
Start with your minimum cash needs this year
It’s tempting to start with the offer letter and work backward, but the faster reality check is your next 12 months. Put a floor under the year: the minimum after-tax cash that has to clear your checking account each month for the non-negotiables—housing, childcare, debt payments, insurance you already pay, and the boring stuff that still counts (utilities, commuting, prescriptions). Then add the lumpy items you can’t pretend won’t happen: annual property tax, car maintenance, holiday travel, a medical procedure you’ve been postponing, a semester bill.
Now run that floor against each offer’s pay cadence and the first-year frictions. A $15,000 raise that arrives biweekly still may not cover a March gap if there’s a sign-on bonus paid “within 60 days,” a benefits waiting period, or a 401(k) match that doesn’t start until month three. If your partner’s income is uncertain, treat it like a variable, not a guarantee. When the minimum cash line is explicit, negotiations get cleaner: you’re not asking for “more,” you’re closing a specific coverage gap.
The mismatch: a bigger salary that shrinks
The bigger salary usually looks decisive until the first paystub reminds you how many hands touch it. Federal and state withholding step up, payroll taxes climb, and the new benefit elections come out of the same check. If the higher-paying offer also leans on an HSA plan with a thinner employer contribution, the “raise” can quietly turn into a higher monthly medical reserve. The mismatch shows up fast: you feel richer in the offer letter and tighter in week three.
What makes this tricky is that some deductions are optional (401(k) deferral, ESPP), and some are not (health premiums, FSA, commuter). A mid-career move often raises the pressure to save, so the first thing you do with the bigger salary is increase retirement contributions—then wonder why take-home barely moves. If one offer includes a strong match but the other expects you to self-fund that gap, the higher cash number can shrink further once you “normalize” savings.
To keep it honest, compare both offers at the same savings settings: same 401(k) percentage, same HSA/FSA choice, same assumed out-of-pocket medical budget. Then look at the after-tax monthly number, not annual salary. That’s where you’ll see whether the bigger headline is actually buying flexibility—or just paying for the benefits you lost.
Benefits that sound guaranteed until they aren’t
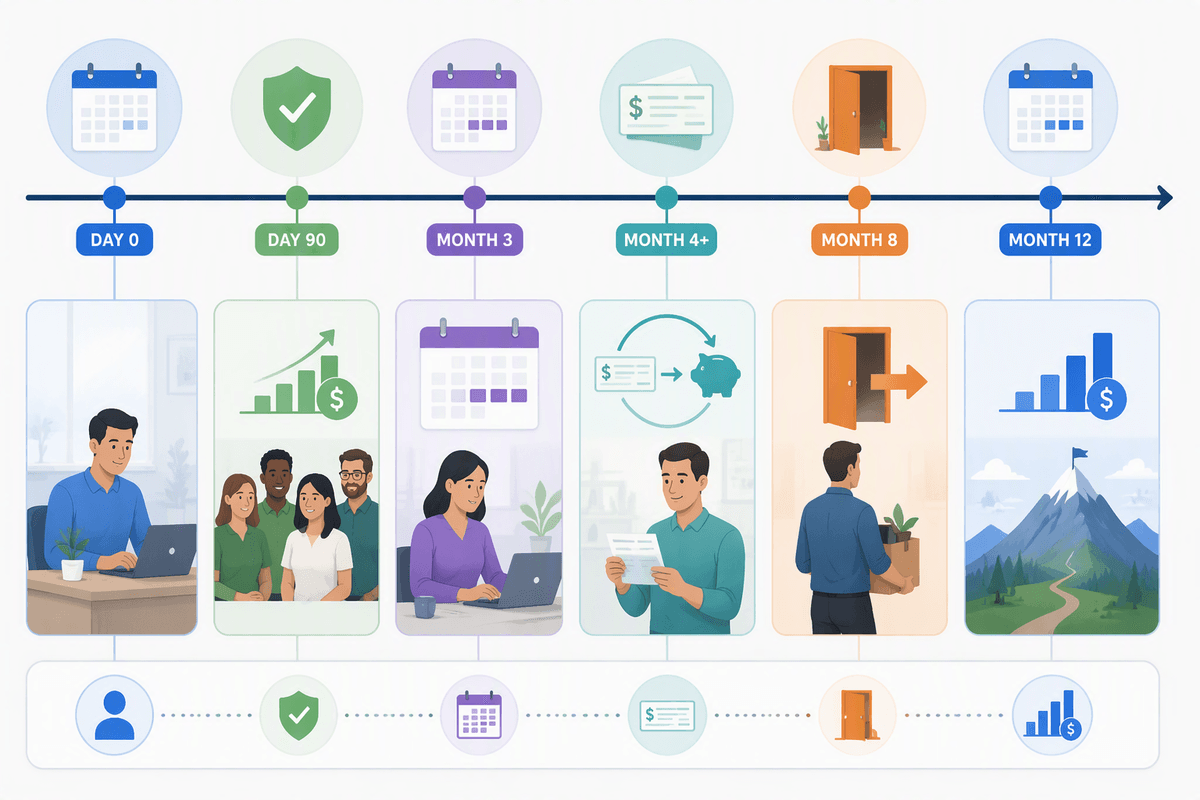
Once the after-tax monthly number is on the table, the “benefits” column starts to matter in a less flattering way. The richer package is often written as if it’s cash, but it’s really a schedule of conditions: eligibility dates, hours requirements, enrollment windows, and plan rules that can change next January. A 6% 401(k) match that starts after 90 days is not worth 6% if you’re likely to leave at month eight, or if the match is “per pay period” with no true-up after a midyear start. Even PTO can be less liquid than it sounds if it’s “unlimited” but culturally discouraged, or if payouts are capped when you exit.
Healthcare is the most fragile promise because the cost shows up right away and the protection only matters when something goes wrong. Two plans with similar premiums can diverge sharply in deductible exposure, out-of-network rules, and whether spouses are surcharged. Add in short-term disability waiting periods and whether employer-paid life insurance is portable, and you end up with a benefit package that works beautifully—until the first disruption forces you to test the fine print.
So the question shifts from “what’s included” to “what still holds if timing slips, health changes, or the role changes.”
Run two stress tests before you negotiate
Before you counter, it helps to run two quick stress tests that assume things don’t go smoothly. The first is a “short-tenure” test: imagine you leave in 9–12 months (bad fit, reorg, family move). What compensation still pays out? Count only what vests, matches without a true-up trap, and bonuses that aren’t “must be employed on payout date.” If the safer package depends on being there on December 31, treat it as uncertain, not earned.
The second is a “bad quarter” test: one unexpected medical year, plus a temporary income wobble at home. Price the worst plausible out-of-pocket under each health plan, then add the cash strain of higher premiums, HSA funding, and any benefit waiting periods. If one offer fails either test, your negotiation target becomes specific: earlier eligibility, a guaranteed true-up, a deductible stipend, or more base to self-insure the gap.
Convert perks into comparable dollars and risks
At this point the spreadsheet usually stalls on the fuzzy perks: “unlimited PTO,” “wellness,” “learning budget,” a better title. The way past it is to turn each item into either (1) dollars that land in your accounts this year or (2) dollars you’d have to spend if it disappears. If the employer covers $450 more per month in premiums, that’s $5,400 of after‑tax value you don’t have to earn. If the HSA seed is $1,000, it’s close to $1,000 because it’s immediate and portable; a year‑end bonus with an “employed on payout date” clause is not.
Do the same with retirement and time. A 5% match on a $140,000 salary is $7,000, but discount it if vesting is 2 years or the match is per‑pay‑period with no true‑up. PTO is only money when it’s usable: if the culture keeps people under two weeks, value it at what you’d realistically take, then ask whether unused time is paid out. The point isn’t precision; it’s forcing every perk to declare its cash value and its failure mode.
Pick the trade-off you can live with
By now, the two offers usually stop looking like “more” versus “less” and start looking like two different ways to carry risk. One keeps cash high and asks you to self-insure: bigger base, thinner match, higher medical exposure, maybe a bonus that could vanish. The other lowers the month-to-month ceiling but quietly removes tail risk: richer employer premiums, steadier retirement funding, clearer disability coverage, fewer timing traps. The constraint that tends to decide it is not optimism—it’s how much volatility your household can absorb before it forces debt, a 401(k) pause, or a rushed job change.
So pick the package whose worst-case outcome you can still live with. If the “bad quarter” test required you to keep $8,000 more in cash reserves under Offer A, treat that as a real cost. If Offer B only works if you stay past a vesting cliff, admit that you’re buying a retention bet. Then negotiate to close the single largest gap you can’t tolerate—earlier eligibility, a true-up, a deductible stipend, or more base—and accept that the remaining trade-off is the one you’re choosing on purpose.