You’ve got extra cash, but two urgent needs
The month finally closes with a little oxygen: bills are paid, the checking account isn’t scraping zero, and there’s a surplus that could actually change something. Then the decision gets awkward. The credit card balance is loud and measurable—interest posting every statement cycle—while the emergency fund is quiet until the day it isn’t. Both feel urgent for different reasons, and the timing is never clean.
In practice, the surplus is being asked to do two incompatible jobs at once: reduce a known, compounding cost, and buy liquidity for an unknown hit. If the surplus is $300–$800, a single car repair can erase months of progress either way, which makes “pick one” feel simpler than it really is.
Your first instinct: crush debt and be done
The impulse is to treat the surplus like a weapon: aim it at the highest-rate balance and keep firing until the number is gone. It’s emotionally clean. A 24% card is charging interest whether life is calm or not, and every extra dollar sent to principal has a visible payoff: fewer months, less interest, a smaller minimum payment trying to follow you into next month. When the surplus is limited, the math feels even more persuasive because the interest savings are immediate and guaranteed.
What sneaks in is the assumption that nothing interrupts the plan. The same $500 that accelerates payoff also leaves less cash sitting around for the boring stuff—tires, medical copays, a broken phone—so the plan becomes fragile. If the emergency lands early, the “crush it” strategy can force a reversal: swiping the card again, paying a fee for a quick loan, or missing the payoff target and watching motivation leak out.
Reality check: the emergency arrives mid-payoff
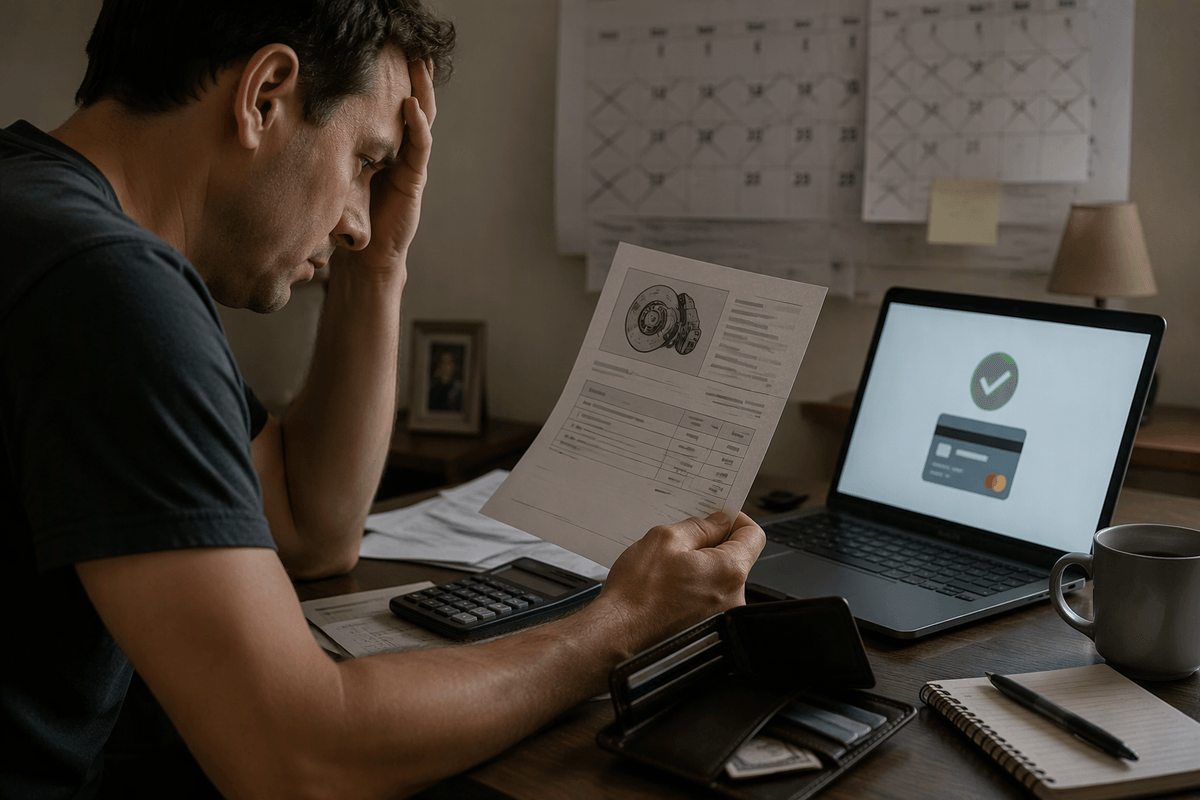
Halfway through the payoff sprint, something ordinary breaks the script. The car needs brakes, the kid’s prescription hits a deductible reset, the landlord announces a rent increase with a short deadline. The timing is what makes it destabilizing: you’ve been sending $500 extra to the card, your cash balance is thinner than usual, and the “one-time” expense doesn’t care about your payoff calendar. You can feel the trade-off in hours, not spreadsheets.
Without a buffer, the options compress fast. Put the $900 repair on the same card you’ve been attacking and you effectively refinance the emergency at 20%–30%, plus you lose some of the principal progress you just paid for. Pull from a near-empty checking account and you risk overdrafts, late fees, or a missed minimum if payroll timing is tight. The frustration isn’t just the cost; it’s the whiplash of paying down debt and then recreating it under pressure.
That’s the real test: a plan that only works when nothing goes wrong isn’t a plan, it’s a good month.
A small buffer changes the entire decision
A small buffer doesn’t feel like progress in the way a shrinking card balance does, but it changes the payoff plan from “fragile” to “resilient” almost immediately. The moment there’s even $500–$1,500 that’s reserved for surprises, the next emergency stops being a refinancing event. Instead of reacting with a swipe at 24% or a rushed loan, the expense gets paid in cash and the debt plan keeps its shape.
The interesting part is that the buffer doesn’t need to be “fully funded” to do its job. It needs to be big enough to cover the most common shocks in your life—deductibles, a basic car repair, travel for a family issue—without forcing new borrowing. That’s a risk threshold, not a motivational milestone. If the surplus is $600 and you divert $200 for two or three months, you’re buying protection against the exact scenario that previously erased $600 of payoff progress in a weekend.
Once that protection exists, throwing every extra dollar at the card becomes easier to defend, because you’re no longer betting the plan on perfect timing. You’re paying for continuity: fewer reversals, fewer fees, and fewer “start over” months.
Then you choose a split that you can defend
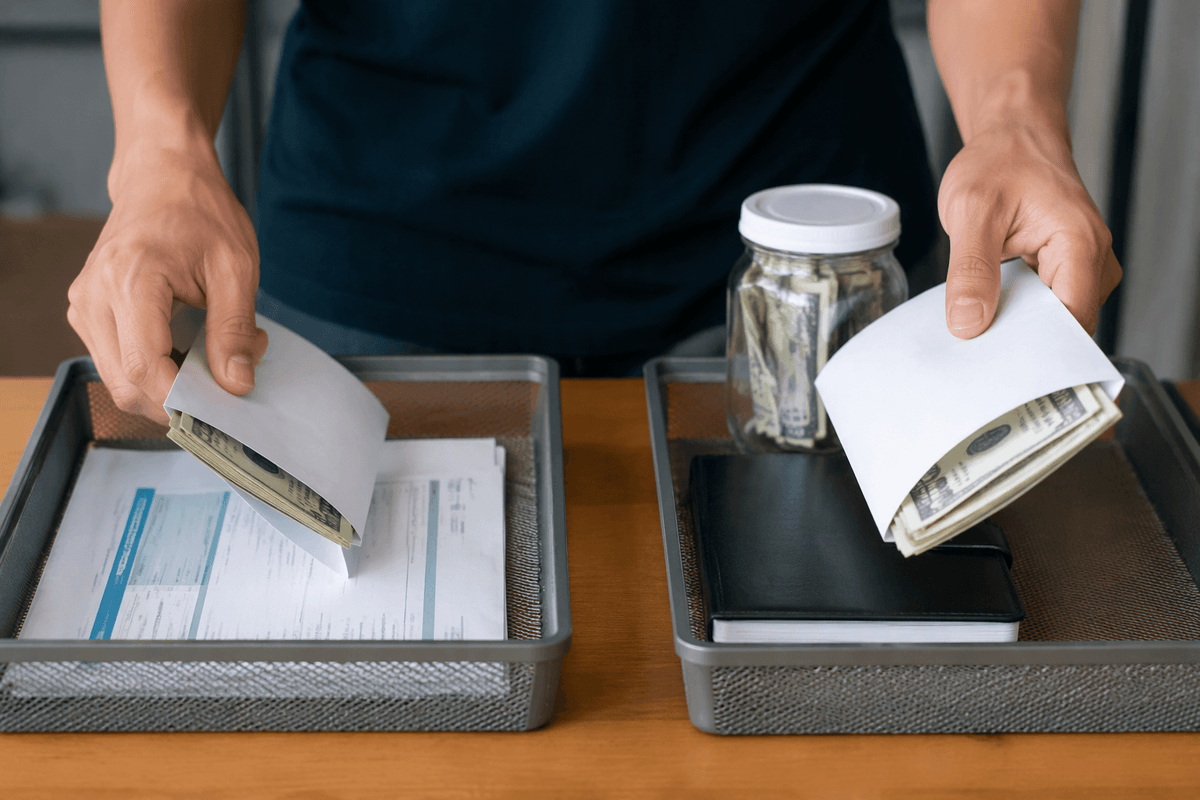
After the buffer exists, the decision shifts from “all debt or all cash” to something more like portfolio management under stress. The split only works if it survives a bad week: a surprise bill, a paycheck delay, a little panic. That’s why the cleanest approach is usually a fixed percentage for a short window—say 70/30 or 80/20—so the plan doesn’t require a fresh debate every payday. The constraint is behavioral as much as financial: if the split feels punitive, it won’t hold.
From there, the numbers get practical. If the card is 22% and the savings account is 4%, debt payoff wins on return, but savings wins on liquidity. So the defensible split is the one that keeps you out of new borrowing while still making the balance move every month. If $600 is the surplus, $450 to debt and $150 to cash is boring, but it’s repeatable; $600 to debt is faster until the first $900 problem shows up.
Once the buffer hits the level that covers your most likely hit, the split can “tilt” automatically toward debt without feeling like a gamble. The point isn’t optimization—it’s choosing a ratio you won’t regret when timing turns against you.
Thresholds that trigger switching gears automatically
After a few months, the split is doing its job, but the real improvement is when it stops being a monthly negotiation. The easiest way to get there is to set two or three numbers that decide for you. One is a cash-floor: if your buffer drops below it, the next surplus goes mostly to rebuilding cash until you’re back above the line. That prevents the common mistake of “staying aggressive” right after an emergency and then needing the card again.
The second is a debt-rate trigger. If the balance you’re paying is above a set APR (for many people, that’s any card in the high teens or 20s), the plan tilts harder toward payoff once the cash-floor is met. A third can be timing: within 30 days of a known expense (insurance renewal, car registration), you temporarily direct the surplus to cash. The constraint isn’t math—it’s avoiding forced borrowing when the calendar gets tight.
With thresholds, the plan behaves consistently even when you don’t feel consistent, which is usually the point.
What you’re really buying: stability, speed, and sleep
After the thresholds are in place, the surplus stops feeling like a moral test and starts acting like a control system. The buffer isn’t “earning” 4% so much as preventing a 24% relapse, plus late fees, plus the lost month where the balance climbs anyway. That’s stability: fewer reversals and fewer forced decisions made on a Tuesday night.
Speed shows up in a quieter way. When emergencies stop landing on the card, the payoff timeline stops stretching and snapping back. The split looks slower on paper, but it produces cleaner, uninterrupted principal reduction.
And sleep is the tell. If the plan leaves you checking balances before every purchase, it’s underfunded on liquidity, even if the interest math is perfect.